Libertax
←Back to LibertaxES

INSIGHTS & ANALYSIS

Liberty, translated into decisions.

Analysis of the tax, regulatory, technology and long-term shifts shaping international business, ownership and private wealth.

Editorial collection reviewed 7 September 2026
Explore by topic

Showing all 134 insights.

No insights foundTry another term or choose a different topic.
A closed border interrupts a person's access to assets that retain their value; two discreet routes lead to other independent jurisdictions.LATEST BRIEFINGINS-20260916-01LIBERTY & EXIT · COUNTRY RISKThe Worst-Case Scenario Is Not a Crash. It Is Your Country.Centuries of defaults, frozen deposits, seizures and closed exchanges show that losing access, convertibility or ownership can be more destructive than a market fall.Read the analysis ↗25 MIN READ
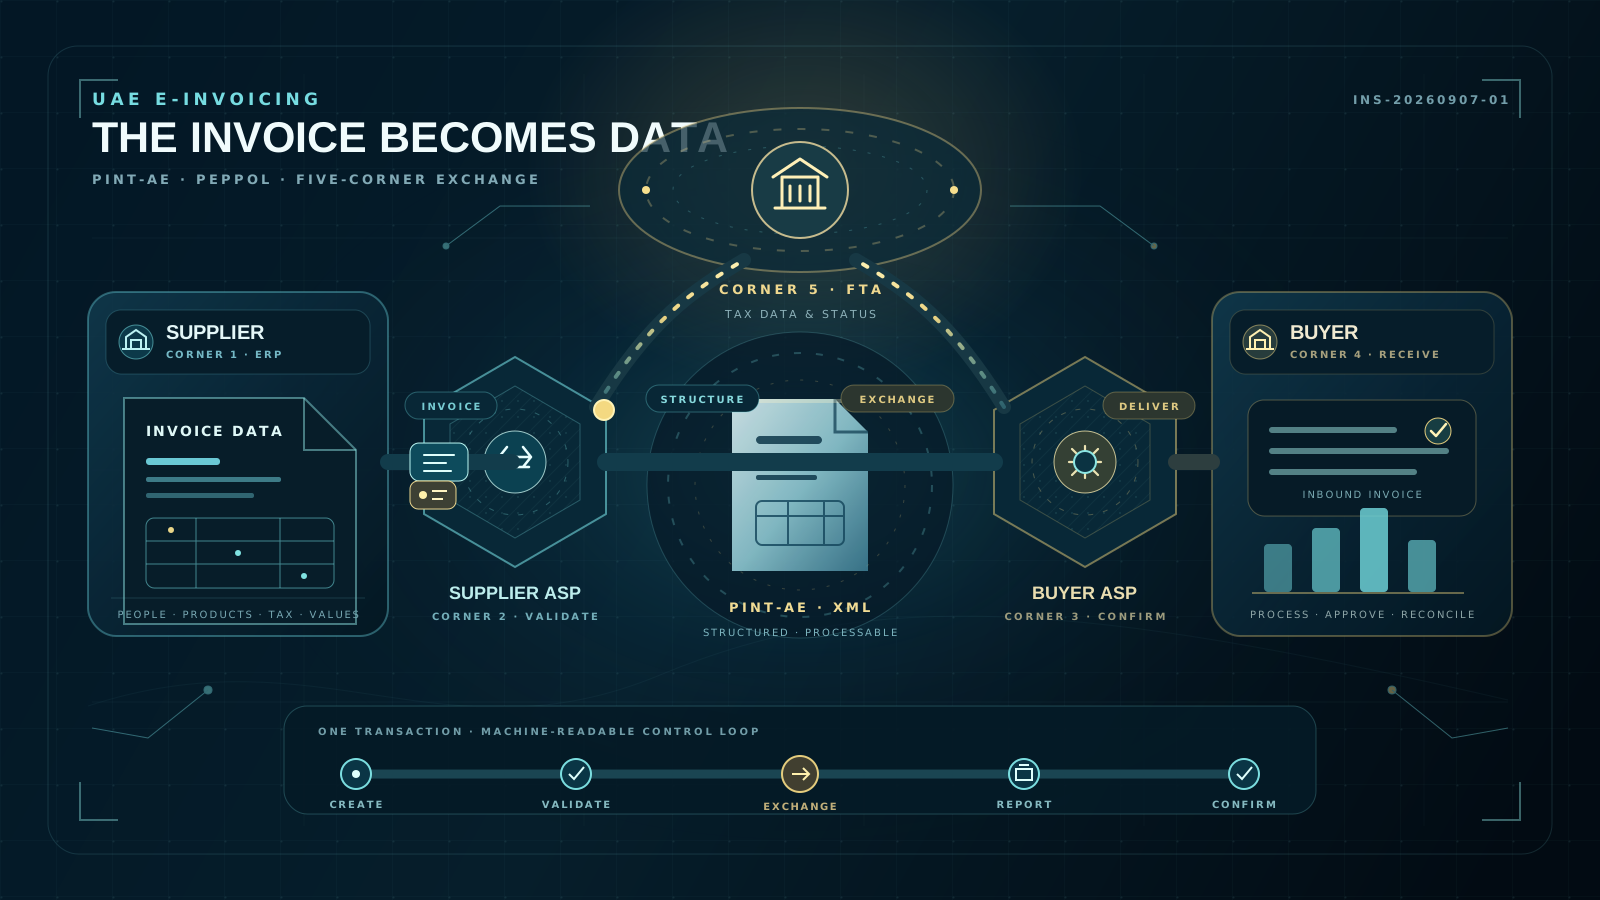
Libertax editorial diagram showing a UAE business turning invoice data into a structured PINT-AE electronic invoice, exchanged through accredited providers and reported to the Federal Tax AuthoritySELECTED ANALYSISINS-20260907-01UAE TAX & BUSINESS · DIGITAL COMPLIANCEUAE e-Invoicing: Why a PDF Will No Longer Be EnoughUAE e-invoicing turns an invoice into structured data exchanged through accredited providers. Understand the deadlines, five-corner flow and practical preparation.Read the analysis ↗9 MIN READ
Libertax editorial diagram connecting a UK company and a UAE company through contracts, functions, decisions and documented intercompany flowsSELECTED ANALYSISINS-20260829-01CORPORATE STRUCTURES · UK & UAEYou Moved to Dubai. Does Your UK Company Still Have a Job?A UK company can remain useful after its founder moves to Dubai. Decide what each company really does before inventing an intercompany fee.Read the analysis ↗8 MIN READ
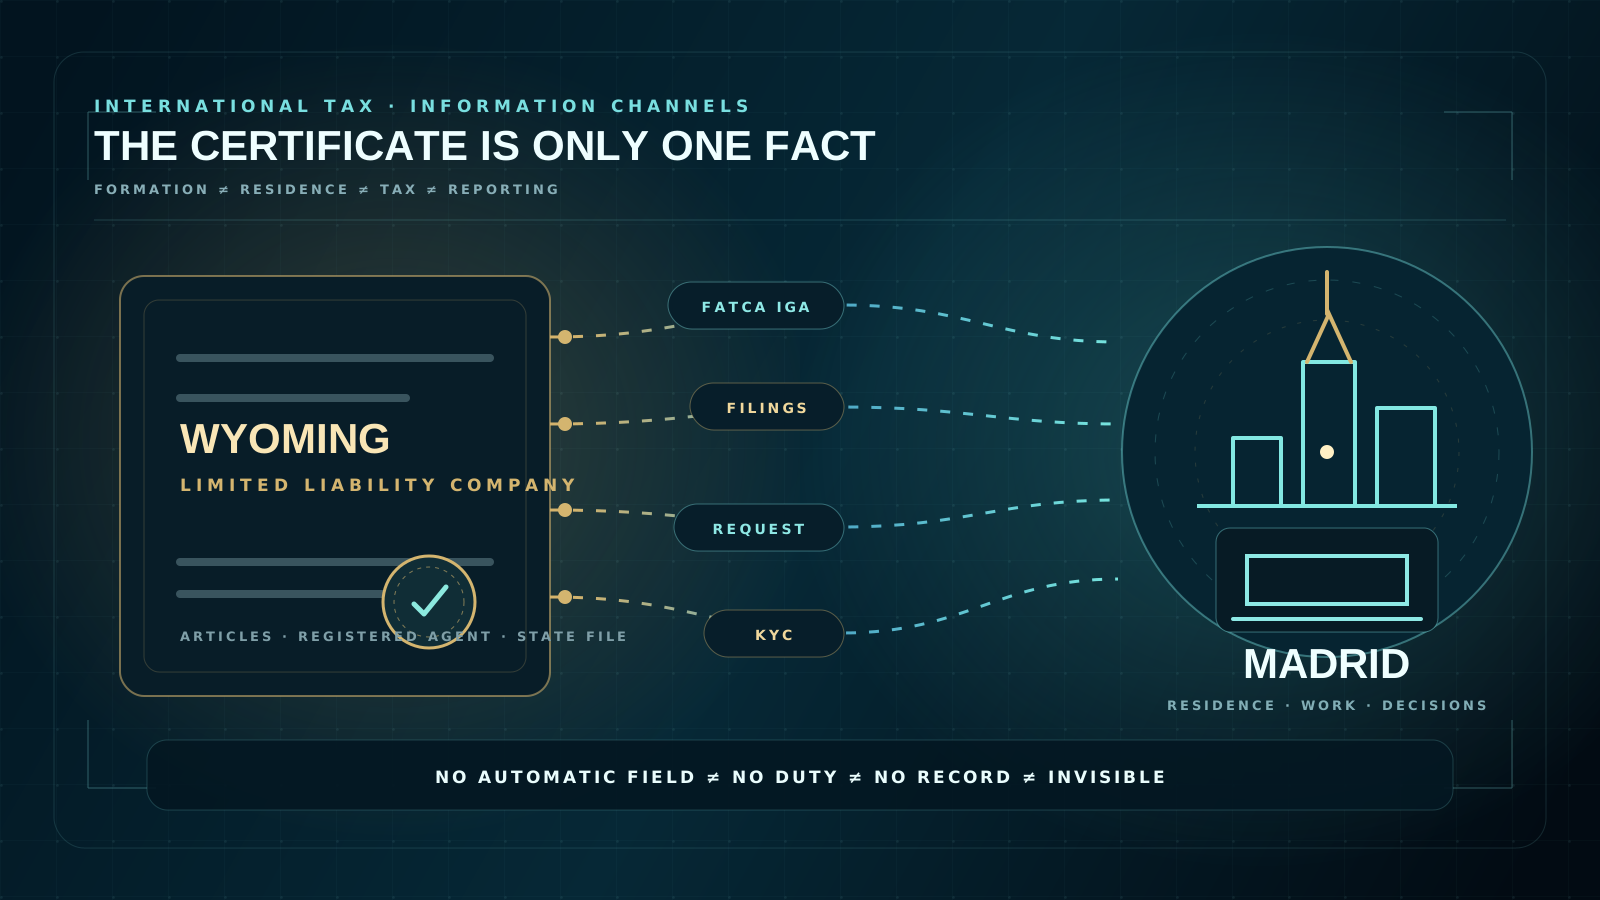
Libertax editorial diagram contrasting a Wyoming LLC certificate with its owner's residence, work, decisions and banking trail in MadridSELECTED ANALYSISINS-20260828-01INTERNATIONAL TAX · FATCA & EVIDENCEThe LLC Was Formed in Wyoming. You Are Still in Madrid.A US LLC and bank account may sit in the United States. They do not carry the owner's residence, work or obligations with them.Read the analysis ↗7 MIN READ
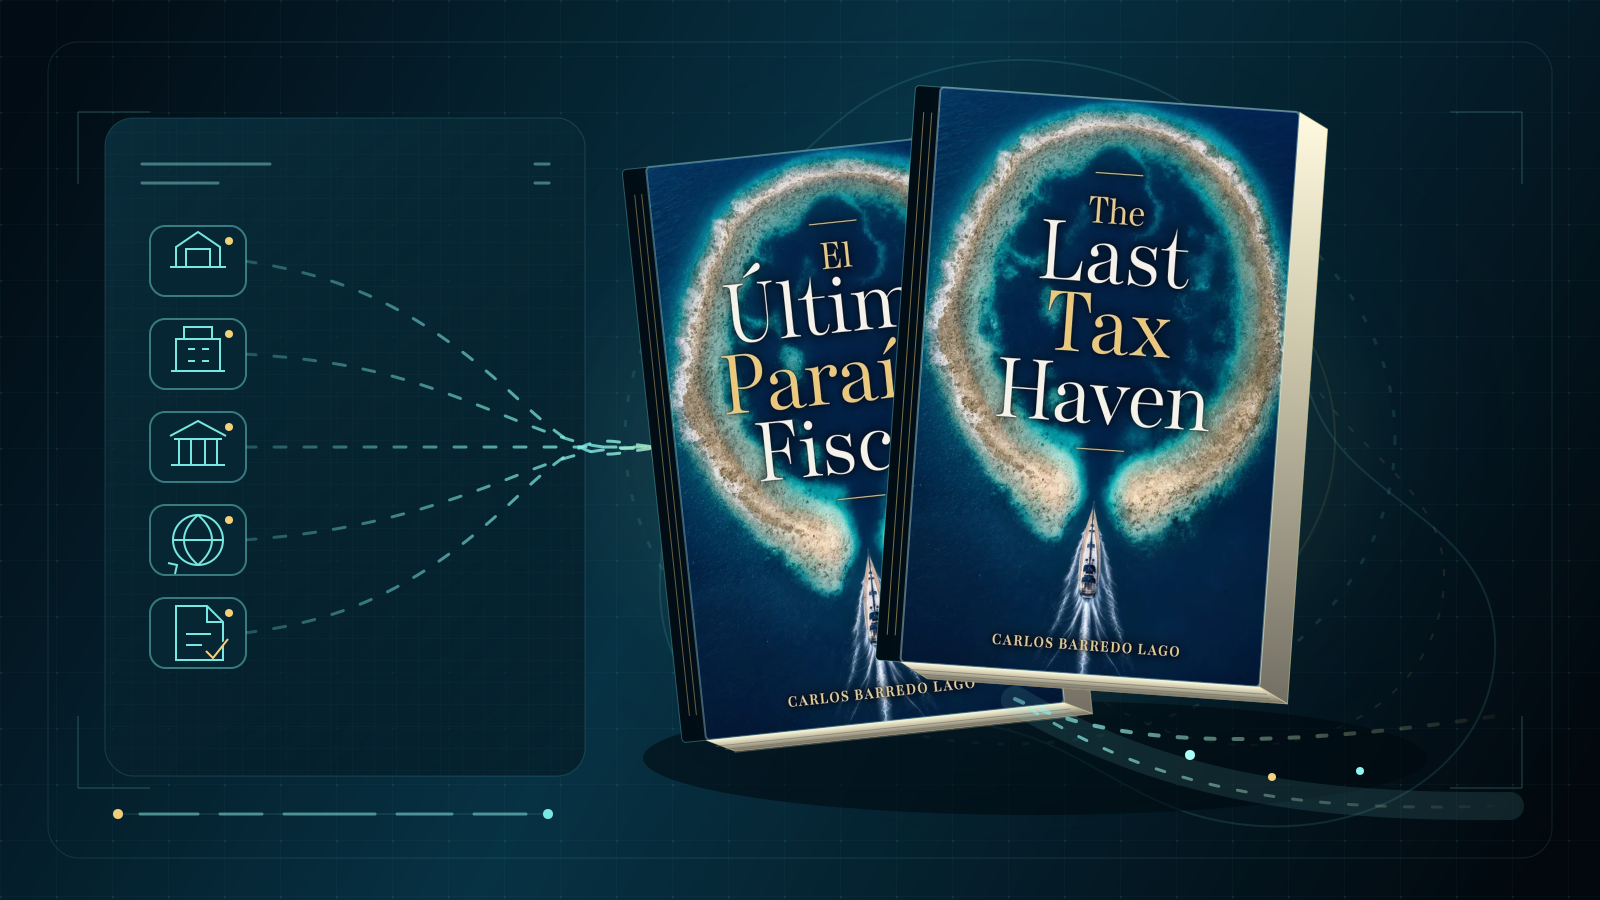
English and Spanish editions of The Last Tax Haven presented as books within a system linking residence, companies, banking, mobility and evidenceSELECTED ANALYSISINS-20260827-01INTERNATIONAL TAX · BOOKThe Last Tax Haven: A Global Life That Holds Together in the Age of AICarlos Barredo Lago examines why residence, companies, banking, mobility and evidence must tell one coherent story in a world where institutions can increasingly connect the facts.Read the analysis ↗5 MIN READ
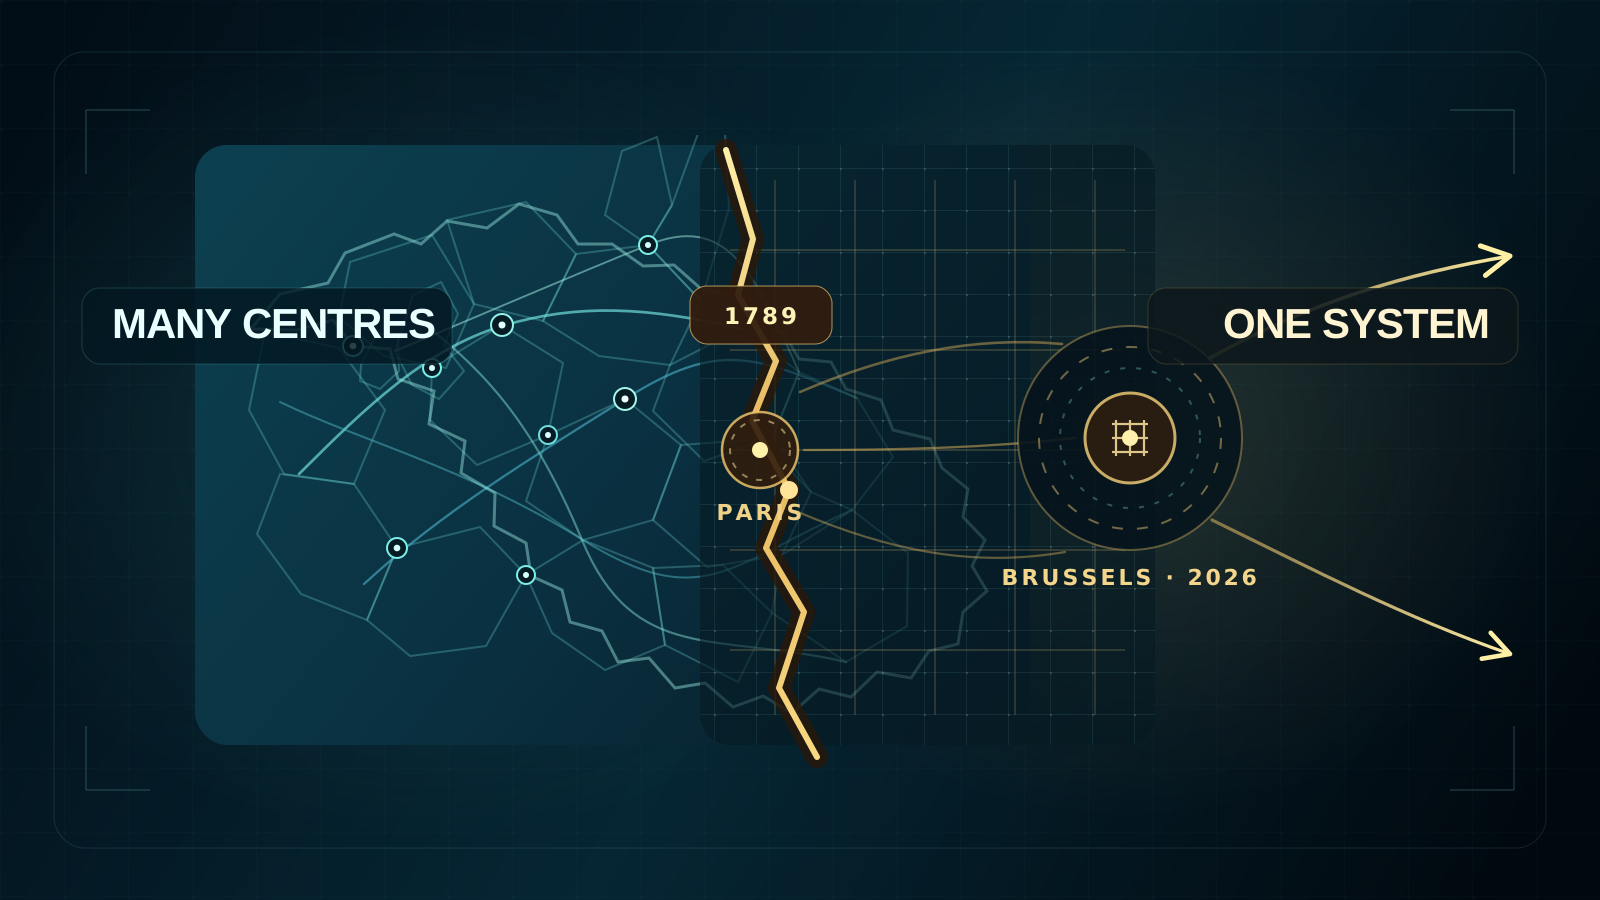
Recognisable map of Europe shown first as a luminous mosaic of competing cities and jurisdictions, then overtaken after a gold 1789 rupture by a rigid grid converging on Brussels in 2026, while several routes escape the system.SELECTED ANALYSISINS-20260813-01PERSPECTIVE · EUROPEAN CENTRALISATIONFrom the Jacobins to Brussels: How Centralisation Is Destroying EuropeThe French Revolution did not merely replace a regime. It erased provincial France, nationalised society and created the nation in arms. The European Union now extends the same centralising instinct through harmonisation, regulation and institutions that cannot possibly possess the knowledge they claim to govern.Read the analysis ↗15 MIN READ
Libertax editorial graphic showing fictional taxable profits falling from £250,000 to £200,000 after a £50,000 charitable donation, with Corporation Tax falling from £62,500 to about £49,250SELECTED ANALYSISINS-20260812-01UK CORPORATION TAX · CHARITABLE GIVINGA £50,000 Charity Donation Does Not Mean £50,000 Less Corporation TaxA practical UK company example showing how charitable donations actually reduce Corporation Tax, how CAF Company Accounts work and why timing and primary-source verification matter.Read the analysis ↗7 MIN READ
Libertax editorial system showing the fixed AED 3 million UAE Small Business Relief revenue threshold, the former 2026 end date and the extended 2029 end dateSELECTED ANALYSISINS-20260810-02UAE CORPORATE TAX · SMALL BUSINESS RELIEFUAE Small Business Relief Extended to 2029: What the AED 3 Million Rule Actually MeansThe UAE has extended Small Business Relief to Tax Periods ending by 31 December 2029. Here is who can qualify, how the AED 3 million Revenue test works and what businesses still need to file.Read the analysis ↗7 MIN READ
Editorial illustration of work, ageing and lifespan assumptions converging into a planning system that preserves several possible futuresSELECTED ANALYSISINS-20260810-01PERSPECTIVE · LONG-TERM PLANNINGWork, Ageing and Lifespan: Planning When the Assumptions MoveHow changes in work, healthy ageing and lifespan could reshape careers, wealth, retirement and long-term planning without making any one forecast inevitable.Read the analysis ↗8 MIN READ
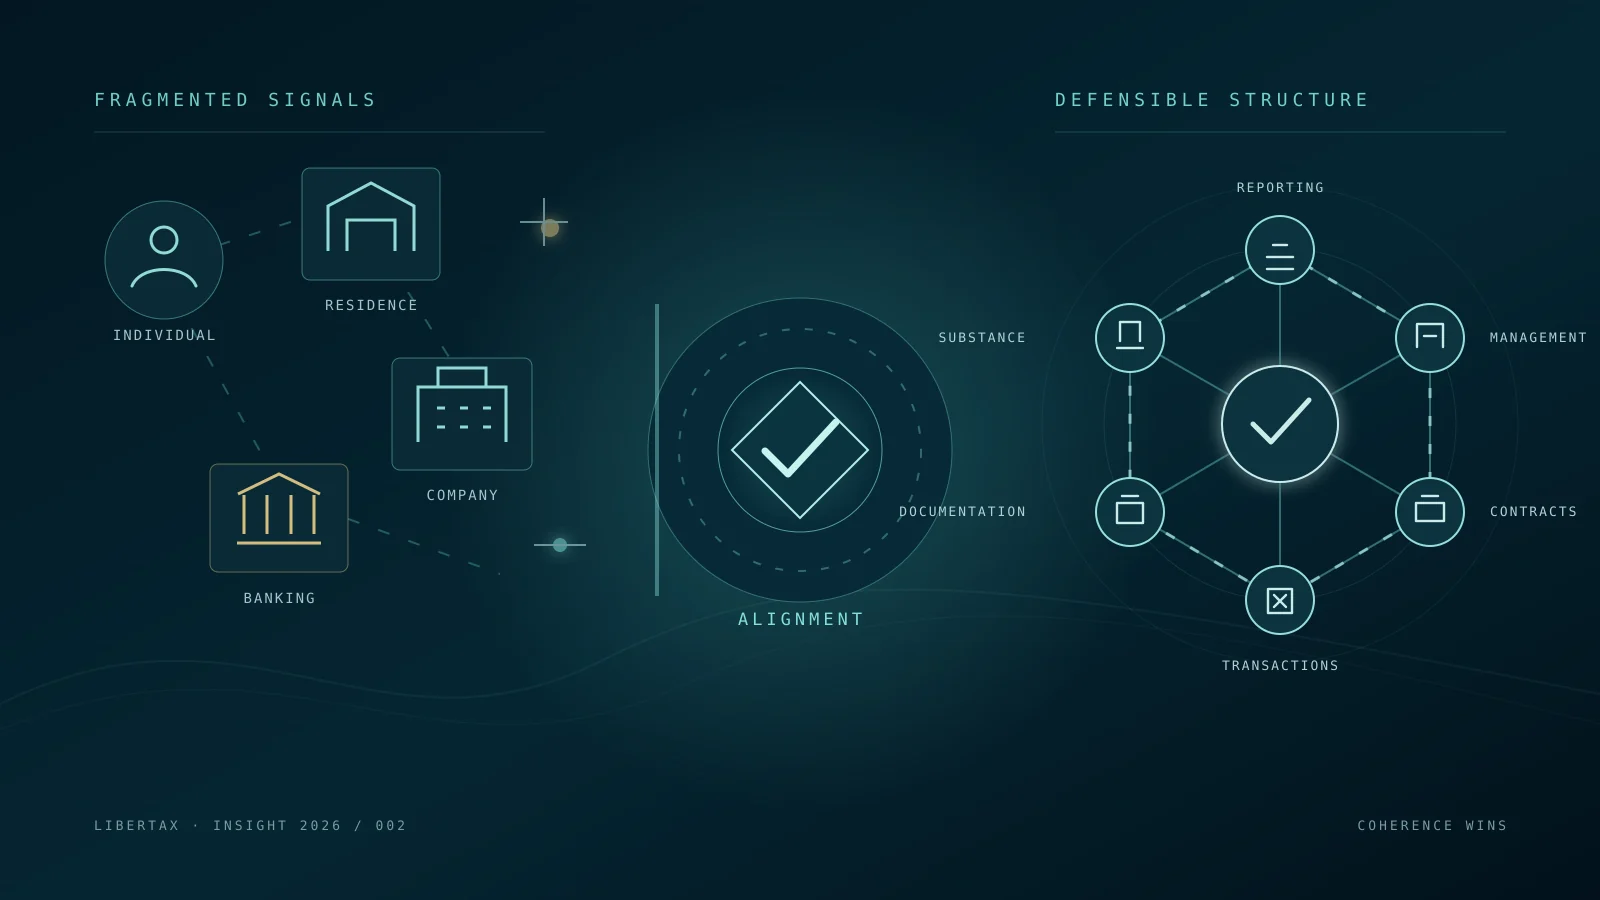
Editorial illustration of fragmented cross-border signals aligning into one coherent international structureSELECTED ANALYSISINS-20260807-01INTERNATIONAL TAX · TAX TECHNOLOGYThe Age of Sloppy Tax Planning Is EndingAI and connected tax data are making poorly designed international structures harder to defend. Why proper tax planning matters more than ever.Read the analysis ↗7 MIN READ
Editorial illustration of wallet and reporting-provider data moving through a global tax transparency networkSELECTED ANALYSISINS-20260731-01VIRTUAL ASSETS · TAX TRANSPARENCYCrypto Tax Transparency in 2026: How CARF Changes International Tax PlanningWhy tax residence, beneficial ownership and transaction records now matter more than where a wallet or exchange is located.Read the analysis ↗8 MIN READ
Libertax editorial visualization for “Do Not Choose the Company before Choosing the Residence”SELECTED ANALYSISINS-20260729-01PRACTICAL MYTHSDo Not Choose the Company before Choosing the ResidenceA company should be the output of an international structuring analysis, not the starting product. Begin with the person, residence, activity and flows.Read the analysis ↗8 MIN READ
Libertax editorial visualization for “The AI Act Meets the AI Omnibus”SELECTED ANALYSISINS-20260727-02AI & BORDERLESS WORK · AI TURNING POINTSThe AI Act Meets the AI OmnibusEurope's AI rulebook reached its general application phase only after the EU had already changed important implementation timelines. That does not prove regulatory failure; it shows the difficulty of governing a technology that moves faster than its standards.Read the analysis ↗4 MIN READ
Libertax editorial visualization for “The Strait of Hormuz: A Narrow Passage That Prices the World”SELECTED ANALYSISINS-20260727-01WORLD IN CONFLICTThe Strait of Hormuz: A Narrow Passage That Prices the WorldThe Strait of Hormuz shows how a narrow geographic chokepoint can transmit military risk into shipping, energy, insurance, working capital and corporate strategy far beyond the Gulf.Read the analysis ↗6 MIN READ
Libertax editorial visualization for “Entity Classification Mismatch: The Hidden Tax in Cross-Border Structures”SELECTED ANALYSISINS-20260630-01PRACTICAL MYTHSEntity Classification Mismatch: The Hidden Tax in Cross-Border StructuresWhen countries classify the same entity differently, the taxpayer, timing, income character, relief and reporting can all diverge.Read the analysis ↗4 MIN READ
Libertax editorial visualization for “Hegemon versus Challenger: The United States and China”SELECTED ANALYSISINS-20260625-01THE NEW WORLD ORDERHegemon versus Challenger: The United States and ChinaUS–China competition is not one trade war. It combines tariffs, export controls, investment restrictions, industrial policy and technological rivalry—and each mechanism creates a different business exposure.Read the analysis ↗3 MIN READ
Libertax editorial visualization for “Portugal's Crypto Reporting Rules Are Becoming More Operational”SELECTED ANALYSISINS-20260603-01TRANSPARENCY & ENFORCEMENT · PORTUGAL FILESPortugal's Crypto Reporting Rules Are Becoming More OperationalPortugal's 2026 framework connects CASP due diligence and annual reporting with DAC8 and CARF, while leaving tax classification separate.Read the analysis ↗4 MIN READ
Libertax editorial visualization for “AI Agents, Permanent Establishment and Management Control”SELECTED ANALYSISINS-20260528-01AI & BORDERLESS WORK · AI & TAX ADMINISTRATIONAI Agents, Permanent Establishment and Management ControlAI agents can execute more business activity without changing a basic tax question: which legally relevant functions, decisions and people connect the company to a jurisdiction? Current rules do not make an AI agent a permanent establishment by itself.Read the analysis ↗5 MIN READ
Libertax editorial visualization for “Substance Is a Design Question, Not a Box-Ticking Exercise”SELECTED ANALYSISINS-20260514-01CORPORATE STRUCTURES · STRUCTURES THAT WORKSubstance Is a Design Question, Not a Box-Ticking ExerciseThere is no single universal substance test. In the UAE, QFZP adequate-substance conditions, effective management, permanent establishment and transfer pricing are related but legally distinct questions.Read the analysis ↗7 MIN READ
Libertax editorial visualization for “The Next Five Years of Tax Competition”30 APR 2026·FROM THE LIBERTAX ARCHIVEINS-20260430-01TAX COMPETITION · GLOBAL TAX ORDERThe Next Five Years of Tax CompetitionPillar Two narrows some forms of corporate rate competition for large multinational groups, but it does not end competition between jurisdictions. It changes the margins on which they compete.Read the analysis ↗7 MIN READ
Libertax editorial visualization for “The World Is More Mobile and More Transparent”24 APR 2026·FROM THE LIBERTAX ARCHIVEINS-20260424-01PHILOSOPHY & STRATEGY · LIBERTAX THESISThe World Is More Mobile and More TransparentInternational mobility and international transparency have expanded at the same time. More cross-border options exist, but incoherent structures are easier to detect and harder to defend.Read the analysis ↗6 MIN READ
Libertax editorial visualization for “Five Years of Libertax: What Changed and What Did Not”09 APR 2026·FROM THE LIBERTAX ARCHIVEINS-20260409-01LIBERTAX ARCHIVE · FIVE YEARS OF LIBERTAXFive Years of Libertax: What Changed and What Did NotOn Libertax’s fifth anniversary, a synthesis of what 2021–2026 changed in international tax, regulation and transparency — and the principles that remained constant.Read the analysis ↗7 MIN READ
Libertax editorial visualization for “The Decline of Europe Is Not Inevitable”29 MAR 2026·FROM THE LIBERTAX ARCHIVEINS-20260329-01THE NEW WORLD ORDERThe Decline of Europe Is Not InevitableEurope's competitiveness problem is real, but decline is a scenario rather than a destiny. The constructive alternative combines scale where scale is necessary with competition, optionality and decentralised experimentation where it is not.Read the analysis ↗8 MIN READ
Libertax editorial visualization for “The UAE Adds an R&D Tax Credit”18 MAR 2026·FROM THE LIBERTAX ARCHIVEINS-20260318-01JURISDICTIONS & TAX REGIMES · UAE TRANSFORMATIONThe UAE Adds an R&D Tax CreditThe UAE R&D Tax Credit applies to qualifying R&D for periods beginning on or after 1 January 2026. It is non-refundable, tiered by qualifying expenditure and R&D staff, and requires pre-approval and evidence.Read the analysis ↗11 MIN READ
Libertax editorial visualization for “Exit Taxes: The State’s Final Claim”19 FEB 2026·FROM THE LIBERTAX ARCHIVEINS-20260219-01LIBERTY & EXITExit Taxes: The State’s Final ClaimExit taxes are not one thing. They can preserve a tax claim over value accrued before assets or residence move, but their design raises hard questions about valuation, liquidity, proportionality and the point at which a jurisdiction's nexus truly ends.Read the analysis ↗7 MIN READ
Libertax editorial visualization for “CARF Exchanges Begin in 2027: Why 2026 Matters”05 FEB 2026·FROM THE LIBERTAX ARCHIVEINS-20260205-01TRANSPARENCY & ENFORCEMENT · FROM CRS TO CARFCARF Exchanges Begin in 2027: Why 2026 MattersThe first CARF exchange cohorts begin in 2027, but CARF is not one global start date. Providers and users need clean residence, identity, control and transaction records before the data begins moving between tax authorities.Read the analysis ↗7 MIN READ
Libertax editorial visualization for “Companies House Is Using AI to Police the Register”22 JAN 2026·FROM THE LIBERTAX ARCHIVEINS-20260122-01AI & BORDERLESS WORK · AI & TAX ADMINISTRATIONCompanies House Is Using AI to Police the RegisterCompanies House is moving beyond passive filing. Identity verification, stronger statutory powers, data analysis and AI-assisted anomaly detection are turning the UK register into a more active integrity system.Read the analysis ↗3 MIN READ
Libertax editorial visualization for “DAC8 Starts: Crypto Tax Transparency Becomes Operational”01 JAN 2026·FROM THE LIBERTAX ARCHIVEINS-20260101-01TRANSPARENCY & ENFORCEMENT · FROM CRS TO CARFDAC8 Starts: Crypto Tax Transparency Becomes OperationalFrom 2026, DAC8 is an operating data problem for in-scope crypto providers: tax residence, self-certification, controlling persons, transaction classification, valuation, remediation and evidence.Read the analysis ↗7 MIN READ
Libertax editorial visualization for “Planning for Legacy NHR After Repeal”11 DEC 2025·FROM THE LIBERTAX ARCHIVEINS-20251211-01JURISDICTIONS & TAX REGIMES · PORTUGAL FILESPlanning for Legacy NHR After RepealExisting NHR beneficiaries may retain their original period, but each year still requires income, source, treaty and evidence review.Read the analysis ↗4 MIN READ
Libertax editorial visualization for “Tax Authorities Will Use AI Before Most Taxpayers Do”01 DEC 2025·FROM THE LIBERTAX ARCHIVEINS-20251201-01AI & BORDERLESS WORK · AI & TAX ADMINISTRATIONTax Authorities Will Use AI Before Most Taxpayers DoThe most immediate tax-administration use of AI is not an autonomous tax assessment. It is earlier in the process: matching data, identifying anomalies, scoring risk and deciding where scarce human audit attention should go.Read the analysis ↗5 MIN READ
Libertax editorial visualization for “AI Agents and the Rise of the One-Person Global Firm”20 NOV 2025·FROM THE LIBERTAX ARCHIVEINS-20251120-01AI & BORDERLESS WORK · AI & PROFESSIONAL WORKAI Agents and the Rise of the One-Person Global FirmAI may reduce the minimum efficient size of a global service business. That does not mean one person can replace every function—or that a digital company becomes legally placeless.Read the analysis ↗4 MIN READ
Libertax editorial visualization for “Companies House Identity Verification: The Transition Year”18 NOV 2025·FROM THE LIBERTAX ARCHIVEINS-20251118-01TRANSPARENCY & ENFORCEMENT · UK CORPORATE TRANSPARENCYCompanies House Identity Verification: The Transition Year18 November 2025 started the UK identity-verification transition; it was not one universal deadline. Directors and PSCs must follow role-specific timing and linkage rules.Read the analysis ↗6 MIN READ
Libertax editorial visualization for “The International Founder’s Compliance File”09 OCT 2025·FROM THE LIBERTAX ARCHIVEINS-20251009-01CORPORATE STRUCTURES · STRUCTURES THAT WORKThe International Founder’s Compliance FileAn international founder needs one living evidence file that connects personal residence, entities, management, ownership, banking, tax and recurring corporate obligations.Read the analysis ↗7 MIN READ
Libertax editorial visualization for “Residence Without Evidence Is a Story, Not a Position”18 SEPT 2025·FROM THE LIBERTAX ARCHIVEINS-20250918-01RESIDENCE & MOBILITY · PRACTICAL MYTHSResidence Without Evidence Is a Story, Not a PositionTax residence is determined by law and facts, but the facts must be provable. UK and Portuguese residence rules show why a calendar or certificate alone is rarely the whole evidence file.Read the analysis ↗7 MIN READ
Libertax editorial visualization for “When the Regulator Says Yes and the Bank Says No”21 AUG 2025·FROM THE LIBERTAX ARCHIVEINS-20250821-01BANKING & SUBSTANCE · BANKING REALITYWhen the Regulator Says Yes and the Bank Says NoThe useful banking question comes before incorporation and licensing: can the planned ownership, activity, geography, flows and evidence survive a realistic onboarding review?Read the analysis ↗7 MIN READ
Libertax editorial visualization for “Small States Can Fail Too”19 JUN 2025·FROM THE LIBERTAX ARCHIVEINS-20250619-01JURISDICTIONAL COMPETITIONSmall States Can Fail TooSmall political scale can shorten feedback loops, but it can also magnify capture, thin capacity, dependency and insider power. Smallness amplifies institutions; it does not replace them.Read the analysis ↗7 MIN READ
Libertax editorial visualization for “Why a Cheap Jurisdiction Can Be Expensive”30 APR 2025·FROM THE LIBERTAX ARCHIVEINS-20250430-01PHILOSOPHY & STRATEGY · TAX PHILOSOPHYWhy a Cheap Jurisdiction Can Be ExpensiveIncorporation fees and headline tax rates are only two lines in the cost of a jurisdiction. Compliance, people, banking, premises, evidence and switching costs can dominate the total.Read the analysis ↗6 MIN READ
Libertax editorial visualization for “The Current US BOI Regime: Domestic Companies Are Exempt”17 APR 2025·FROM THE LIBERTAX ARCHIVEINS-20250417-01TRANSPARENCY & ENFORCEMENT · THE TRANSPARENT WORLDThe Current US BOI Regime: Domestic Companies Are ExemptUnder FinCEN's current BOI framework, entities created in the United States are exempt from federal CTA reporting, while certain foreign entities registered in the US remain in scope.Read the analysis ↗6 MIN READ
Libertax editorial visualization for “Banking Risk Belongs Inside Tax Planning”08 APR 2025·FROM THE LIBERTAX ARCHIVEINS-20250408-01BANKING & SUBSTANCE · BANKING REALITYBanking Risk Belongs Inside Tax PlanningA tax-efficient structure is incomplete if ownership, activity, geography, flows and evidence cannot support a realistic banking relationship.Read the analysis ↗6 MIN READ
Libertax editorial visualization for “The Death of the Set-and-Forget International Structure”07 APR 2025·FROM THE LIBERTAX ARCHIVEINS-20250407-01CORPORATE STRUCTURES · STRUCTURES THAT WORKThe Death of the Set-and-Forget International StructureAn international structure can become incoherent when the person's residence, business, ownership, banking or rules change. Formation is the beginning of maintenance, not the end.Read the analysis ↗6 MIN READ
Libertax editorial visualization for “The End of the UK Non-Dom Era”06 APR 2025·FROM THE LIBERTAX ARCHIVEINS-20250406-01JURISDICTIONS & TAX REGIMES · UK TAX RESETThe End of the UK Non-Dom EraWhat changed on 6 April 2025 when the UK replaced the remittance-basis system with a residence-based foreign income and gains regime.Read the analysis ↗5 MIN READ
Libertax editorial visualization for “FinCEN Reverses Course on Domestic BOI Reporting”26 MAR 2025·FROM THE LIBERTAX ARCHIVEINS-20250326-01TRANSPARENCY & ENFORCEMENT · THE TRANSPARENT WORLDFinCEN Reverses Course on Domestic BOI ReportingHow the U.S. beneficial-ownership reporting regime moved from a broad domestic rollout to a March 2025 exemption for U.S.-created entities.Read the analysis ↗6 MIN READ
Libertax editorial visualization for “Bitcoin as Exit Technology”10 MAR 2025·FROM THE LIBERTAX ARCHIVEINS-20250310-01LIBERTY & EXITBitcoin as Exit TechnologyBitcoin can reduce dependence on particular banks, custodians and payment rails. It does not provide automatic exit from tax residence, reporting, law, infrastructure or operational risk.Read the analysis ↗7 MIN READ
Libertax editorial visualization for “Build the Source-of-Wealth File Before the Bank Asks”15 FEB 2025·FROM THE LIBERTAX ARCHIVEINS-20250215-01BANKING & SUBSTANCE · BANKING REALITYBuild the Source-of-Wealth File Before the Bank AsksSource of wealth is a history of how overall wealth was accumulated. A balance today is not the same thing as evidence of the economic events that created it.Read the analysis ↗6 MIN READ
Libertax editorial visualization for “Canada Defers Its Capital-Gains Increase”31 JAN 2025·FROM THE LIBERTAX ARCHIVEINS-20250131-01HIGH-TAX POLICY · TAX PRESSURECanada Defers Its Capital-Gains IncreaseWhat changed on 31 January 2025: the deferral, CRA's return to the enacted one-half inclusion rate, corrective reassessments and the proposal's later cancellation.Read the analysis ↗4 MIN READ
Libertax editorial visualization for “Why Europe Produces Research but Struggles to Scale Companies”15 JAN 2025·FROM THE LIBERTAX ARCHIVEINS-20250115-01THE NEW WORLD ORDERWhy Europe Produces Research but Struggles to Scale CompaniesEurope's innovation problem is not simply a shortage of ideas. The harder question is why promising firms so often face weaker growth capital, fragmented markets and greater difficulty scaling into global companies.Read the analysis ↗3 MIN READ
Libertax editorial visualization for “The UAE Joins Pillar Two Through a Domestic Top-up Tax”01 JAN 2025·FROM THE LIBERTAX ARCHIVEINS-20250101-01TAX COMPETITION · GLOBAL TAX ORDERThe UAE Joins Pillar Two Through a Domestic Top-up TaxHow the UAE’s Domestic Minimum Top-up Tax brought Pillar Two into the Emirates for in-scope multinational groups without turning the ordinary UAE Corporate Tax rate into 15% for every company.Read the analysis ↗6 MIN READ
Libertax editorial visualization for “Europe Regulated While America and China Built”12 DEC 2024·FROM THE LIBERTAX ARCHIVEINS-20241212-01THE NEW WORLD ORDEREurope Regulated While America and China BuiltEurope does have a scale, capital and fragmentation problem. But the claim that Europe only regulates while the United States and China innovate is too crude. The evidence supports a narrower and more useful diagnosis.Read the analysis ↗6 MIN READ
Libertax editorial visualization for “Canada’s Capital-Gains Proposal and the Cost of Policy Uncertainty”01 DEC 2024·FROM THE LIBERTAX ARCHIVEINS-20241201-01HIGH-TAX POLICY · TAX PRESSURECanada’s Capital-Gains Proposal and the Cost of Policy UncertaintyFrom the 1 December 2024 archive date, how Canada’s proposed capital-gains inclusion-rate increase forced taxpayers to plan around a rule that was being administered before its legislative future was settled.Read the analysis ↗6 MIN READ
Libertax editorial visualization for “Why a Bank May Restrict an Account Before the Compliance Review Is Finished”30 NOV 2024·FROM THE LIBERTAX ARCHIVEINS-20241130-01BANKING & SUBSTANCE · BANKING REALITYWhy a Bank May Restrict an Account Before the Compliance Review Is FinishedOngoing customer due diligence can trigger questions or restrictions when activity no longer matches the expected profile. That does not prove wrongdoing, and bank procedures are not universal.Read the analysis ↗6 MIN READ
Libertax editorial visualization for “Dubai Residential Property: Personal Ownership or a UAE Company?”22 OCT 2024·FROM THE LIBERTAX ARCHIVEINS-20241022-01CORPORATE STRUCTURES · STRUCTURES THAT WORKDubai Residential Property: Personal Ownership or a UAE Company?For a Dubai home held for residential rent, personal and company ownership create different Corporate Tax, title, accounting and exit consequences.Read the analysis ↗6 MIN READ
Libertax editorial visualization for “Economic Substance Reporting Ends, but Substance Does Not”14 OCT 2024·FROM THE LIBERTAX ARCHIVEINS-20241014-01CORPORATE STRUCTURES · UAE CORPORATE TAXEconomic Substance Reporting Ends, but Substance Does NotThe UAE ended ESR notifications and reports for financial years ending after 31 December 2022. That did not eliminate separate substance, management, transfer-pricing and evidence questions under other regimes.Read the analysis ↗11 MIN READ
Libertax editorial visualization for “The Draghi Report: The Day Europe Admitted the Problem”09 SEPT 2024·FROM THE LIBERTAX ARCHIVEINS-20240909-01THE NEW WORLD ORDERThe Draghi Report: The Day Europe Admitted the ProblemMario Draghi's 2024 competitiveness report turned concerns about European productivity, energy, investment and fragmentation into an official institutional diagnosis.Read the analysis ↗3 MIN READ
Libertax editorial visualization for “The EU AI Act Enters into Force”01 AUG 2024·FROM THE LIBERTAX ARCHIVEINS-20240801-01AI & BORDERLESS WORK · AI TURNING POINTSThe EU AI Act Enters into ForceOn 1 August 2024, the EU AI Act entered into force. The turning point was Europe's decision to regulate artificial intelligence through a horizontal, risk-based framework before the technology had stopped moving.Read the analysis ↗4 MIN READ
Libertax editorial visualization for “SaaS Sales Tax: Incorporation Is Not the Nexus Analysis”31 JUL 2024·FROM THE LIBERTAX ARCHIVEINS-20240731-01DIGITAL TAX · DIGITAL BUSINESS TAXSaaS Sales Tax: Incorporation Is Not the Nexus AnalysisUS sales-tax exposure for SaaS depends on nexus, product taxability, customer location and marketplace rules. California and New York show why the state of incorporation is not the answer.Read the analysis ↗7 MIN READ
Libertax editorial visualization for “An LLC Can Die Administratively While the Business Continues”15 JUL 2024·FROM THE LIBERTAX ARCHIVEINS-20240715-01CORPORATE STRUCTURES · THE LLC FILESAn LLC Can Die Administratively While the Business ContinuesUS LLC maintenance is state-specific. Missed annual reports, taxes or registered-agent obligations can damage good standing or lead to administrative dissolution even while commercial activity continues.Read the analysis ↗7 MIN READ
Libertax editorial visualization for “The Sovereign Individual Was Right—and Wrong”08 JUL 2024·FROM THE LIBERTAX ARCHIVEINS-20240708-01LIBERTY & EXITThe Sovereign Individual Was Right—and WrongThe information age did make work, capital and identity more portable. It did not make the state disappear. Technology increased private exit capacity while states built unprecedented systems of coordination and transparency.Read the analysis ↗8 MIN READ
Libertax editorial visualization for “The Form 5472 and 1120 Myth”30 JUN 2024·FROM THE LIBERTAX ARCHIVEINS-20240630-01CORPORATE STRUCTURES · THE LLC FILESThe Form 5472 and 1120 MythA foreign-owned US disregarded entity can have federal information-reporting obligations even when its income-tax treatment leads people to assume there is nothing to file.Read the analysis ↗5 MIN READ
Libertax editorial visualization for “The Right to Exit”22 JUN 2024·FROM THE LIBERTAX ARCHIVEINS-20240622-01LIBERTY & EXITThe Right to ExitPolitical voice matters, but freedom is incomplete if leaving a jurisdiction is impossible in practice. The right to exit is fundamental, while accrued legal and tax obligations do not simply disappear at the border.Read the analysis ↗7 MIN READ
Libertax editorial visualization for “IFICI Replaces NHR: Narrower Incentive, Different Policy”31 MAY 2024·FROM THE LIBERTAX ARCHIVEINS-20240531-01JURISDICTIONS & TAX REGIMES · PORTUGAL FILESIFICI Replaces NHR: Narrower Incentive, Different PolicyPortugal's IFICI is a targeted research and innovation incentive, not a general rebranding of the former NHR regime.Read the analysis ↗4 MIN READ
Libertax editorial visualization for “Subsidiarity Is an Institutional Technology”24 MAY 2024·FROM THE LIBERTAX ARCHIVEINS-20240524-01JURISDICTIONAL COMPETITIONSubsidiarity Is an Institutional TechnologySubsidiarity is more useful as a decision rule than as a political slogan: keep authority at the smallest level that can handle the problem, its spillovers and the necessary capacity.Read the analysis ↗8 MIN READ
Libertax editorial visualization for “The Documents That Saved Transitional NHR Applications”16 MAY 2024·FROM THE LIBERTAX ARCHIVEINS-20240516-01JURISDICTIONS & TAX REGIMES · PORTUGAL FILESThe Documents That Saved Transitional NHR ApplicationsPortugal's transitional NHR route depended on dated evidence of a prior link; documents supported eligibility but did not guarantee it.Read the analysis ↗4 MIN READ
Libertax editorial visualization for “A Tax Residence Certificate Is Evidence, Not Magic”04 MAY 2024·FROM THE LIBERTAX ARCHIVEINS-20240504-01RESIDENCE & MOBILITY · PRACTICAL MYTHSA Tax Residence Certificate Is Evidence, Not MagicA tax residence certificate can be important evidence, but it does not replace domestic residence rules or automatically defeat a competing claim from another country. The UAE–UK treaty shows why.Read the analysis ↗6 MIN READ
Libertax editorial visualization for “The Accounting Work That Formation Quotes Forget”01 MAY 2024·FROM THE LIBERTAX ARCHIVEINS-20240501-01CORPORATE STRUCTURES · STRUCTURES THAT WORKThe Accounting Work That Formation Quotes ForgetA May 2024 retrospective on why UAE bookkeeping, annual accounts, audit, Corporate Tax and VAT were already separate post-formation tasks.Read the analysis ↗5 MIN READ
Libertax editorial visualization for “Why Small States Often Govern Better”25 APR 2024·FROM THE LIBERTAX ARCHIVEINS-20240425-01JURISDICTIONAL COMPETITIONWhy Small States Often Govern BetterSmall states do not govern better because they are small. Smaller scale can improve feedback, accountability and experimentation when it is combined with openness, institutional capacity and real competition.Read the analysis ↗7 MIN READ
Libertax editorial visualization for “Company Formation Is the Beginning, Not the Product”19 APR 2024·FROM THE LIBERTAX ARCHIVEINS-20240419-01CORPORATE STRUCTURES · STRUCTURES THAT WORKCompany Formation Is the Beginning, Not the ProductA UAE licence creates a vehicle; operating it requires separate tax, accounting, renewal, corporate-record and closure work.Read the analysis ↗5 MIN READ
Libertax editorial visualization for “From Passive Register to Active Corporate Gatekeeper”31 DEC 2023·FROM THE LIBERTAX ARCHIVEINS-20231231-01TRANSPARENCY & ENFORCEMENT · THE TRANSPARENT WORLDFrom Passive Register to Active Corporate GatekeeperHow the UK’s 2023 Economic Crime and Corporate Transparency Act changed Companies House from a filing repository toward an identity-and-integrity gatekeeper.Read the analysis ↗5 MIN READ
Libertax editorial visualization for “Portugal Ends NHR: Why Successful Regimes Become Political Targets”15 DEC 2023·FROM THE LIBERTAX ARCHIVEINS-20231215-01JURISDICTIONS & TAX REGIMES · PORTUGAL FILESPortugal Ends NHR: Why Successful Regimes Become Political TargetsFrom the December 2023 archive date, how Portugal moved to close ordinary access to NHR, why the political decision preceded final publication of the law, and what the transition still means today.Read the analysis ↗5 MIN READ
Libertax editorial visualization for “AI as Operating Leverage for a Small Professional Firm”11 DEC 2023·FROM THE LIBERTAX ARCHIVEINS-20231211-01AI & BORDERLESS WORK · AI & PROFESSIONAL WORKAI as Operating Leverage for a Small Professional FirmThe strongest case for AI in a small professional firm is not full automation. It is the ability to reduce repetitive cognitive work while preserving expert judgment and accountability.Read the analysis ↗4 MIN READ
Libertax editorial visualization for “NHR Was Never a Blanket Foreign-Income Exemption”30 NOV 2023·FROM THE LIBERTAX ARCHIVEINS-20231130-01JURISDICTIONS & TAX REGIMES · PORTUGAL FILESNHR Was Never a Blanket Foreign-Income ExemptionHistoric NHR treatment depended on income category, source, activity, payer and treaty; the status alone never answered the tax question.Read the analysis ↗4 MIN READ
Libertax editorial visualization for “Shakira Settles: Residence, Evidence and the Cost of Litigation”20 NOV 2023·FROM THE LIBERTAX ARCHIVEINS-20231120-01CASES & COURTS · CASES THAT MATTERShakira Settles: Residence, Evidence and the Cost of LitigationWhat Shakira’s 2023 Spanish tax settlement shows about residence disputes: the decisive questions are factual, year-specific and expensive to litigate.Read the analysis ↗5 MIN READ
Libertax editorial visualization for “Portugal Signs Up for Crypto Information Exchange”10 NOV 2023·FROM THE LIBERTAX ARCHIVEINS-20231110-01TRANSPARENCY & ENFORCEMENT · FROM CRS TO CARFPortugal Signs Up for Crypto Information ExchangePortugal's 2023 CARF commitment signalled future automatic exchange, not an immediate tax or an exchange that began in 2023.Read the analysis ↗4 MIN READ
Libertax editorial visualization for “Xabi Alonso Won: When Refusing a Tax Settlement Pays Off”25 OCT 2023·FROM THE LIBERTAX ARCHIVEINS-20231025-01CASES & COURTS · CASES THAT MATTERXabi Alonso Won: When Refusing a Tax Settlement Pays OffWhat the Spanish Supreme Court’s 2023 decision in Xabi Alonso’s tax case actually proves — and why one successful defence cannot be turned into a universal litigation strategy.Read the analysis ↗5 MIN READ
Libertax editorial visualization for “Flag Theory after CRS and CARF: Diversification without Opacity”21 OCT 2023·FROM THE LIBERTAX ARCHIVEINS-20231021-01LIBERTY & EXITFlag Theory after CRS and CARF: Diversification without OpacityFlag Theory still has value in a transparent world, but its purpose has changed: diversify jurisdictional dependencies without pretending that residence, ownership or assets can remain invisible.Read the analysis ↗7 MIN READ
Libertax editorial visualization for “DAC8: Europe Extends Automatic Tax Transparency to Crypto”17 OCT 2023·FROM THE LIBERTAX ARCHIVEINS-20231017-01TRANSPARENCY & ENFORCEMENT · FROM CRS TO CARFDAC8: Europe Extends Automatic Tax Transparency to CryptoWhy the EU’s 2023 DAC8 directive mattered and what changed when crypto due diligence and reporting moved from future policy to an operational 2026 compliance system.Read the analysis ↗4 MIN READ
Editorial illustration of an organised corporate tax system with accounting layers, connected entities and a free-zone boundarySELECTED ANALYSISINS-20230919-01UAE · CORPORATE TAXThe Evolution of Corporate Tax in the UAEA practical view of the UAE corporate tax framework and the discipline required to adapt structures responsibly.Read the analysis ↗7 MIN READ
Editorial illustration of asset records, ownership documents and transaction evidence converging into a verified financial profileSELECTED ANALYSISINS-20230904-01PRIVATE CAPITAL · EVIDENCEProof of Wealth: A Balance Is Not an ExplanationWhy balances, ownership records and transaction evidence must form one coherent account of how wealth was created and how specific funds moved.Read the analysis ↗8 MIN READ
Libertax editorial visualization for “A US LLC Changes Character at the Border”31 AUG 2023·FROM THE LIBERTAX ARCHIVEINS-20230831-01CORPORATE STRUCTURES · THE LLC FILESA US LLC Changes Character at the BorderUS federal tax classification does not travel automatically: another country may identify a different taxpayer, income character or timing.Read the analysis ↗4 MIN READ
Libertax editorial visualization for “Participation Exemption Is Not a Free Pass”15 AUG 2023·FROM THE LIBERTAX ARCHIVEINS-20230815-01CORPORATE STRUCTURES · PRACTICAL MYTHSParticipation Exemption Is Not a Free PassThe UAE participation exemption can exempt qualifying dividends and gains, but only after the participation, holding and other statutory conditions are tested. It does not erase withholding, treaty or residence questions elsewhere.Read the analysis ↗7 MIN READ
Libertax editorial visualization for “Regulatory Approval Is Not Bankability”07 AUG 2023·FROM THE LIBERTAX ARCHIVEINS-20230807-01BANKING & SUBSTANCE · BANKING REALITYRegulatory Approval Is Not BankabilityA licence and a bank account answer different risk questions. Regulatory approval can strengthen a business case, but it does not create a right to banking.Read the analysis ↗5 MIN READ
Libertax editorial visualization for “Personal Crypto Gains and Corporate Crypto Gains Are Different Questions”31 JUL 2023·FROM THE LIBERTAX ARCHIVEINS-20230731-01CRYPTO & DIGITAL ASSETS · PRACTICAL MYTHSPersonal Crypto Gains and Corporate Crypto Gains Are Different QuestionsThe asset label does not decide the taxpayer. In the UAE, a natural person's personal investment and a company's crypto activity begin from different Corporate Tax rules.Read the analysis ↗7 MIN READ
Libertax editorial visualization for “You Can Have a Crypto Licence and Still Have No Bank Account”21 JUL 2023·FROM THE LIBERTAX ARCHIVEINS-20230721-01BANKING & SUBSTANCE · BANKING REALITYYou Can Have a Crypto Licence and Still Have No Bank AccountA crypto regulator decides whether a firm may conduct regulated activity. A bank separately decides whether it can understand, monitor and accept the relationship.Read the analysis ↗7 MIN READ
Libertax editorial visualization for “Free Zone 0% Is a Conditional Regime, Not a Default”01 JUL 2023·FROM THE LIBERTAX ARCHIVEINS-20230701-01JURISDICTIONS & TAX REGIMES · UAE CORPORATE TAXFree Zone 0% Is a Conditional Regime, Not a DefaultA UAE Free Zone licence does not by itself produce a 0% Corporate Tax outcome. The special treatment depends on QFZP status, Qualifying Income, activities, substance, transfer pricing, audit and other conditions.Read the analysis ↗10 MIN READ
Libertax editorial visualization for “Stablecoins Become the First MiCA Test”30 JUN 2023·FROM THE LIBERTAX ARCHIVEINS-20230630-01CRYPTO & DIGITAL ASSETS · CRYPTO TURNING POINTSStablecoins Become the First MiCA TestMiCA's stablecoin regime is not one rule for one product. Asset-referenced tokens and e-money tokens sit in different legal architectures for issuance, reserves, redemption, governance and capital.Read the analysis ↗7 MIN READ
Libertax editorial visualization for “UAE Corporate Tax Becomes Real”01 JUN 2023·FROM THE LIBERTAX ARCHIVEINS-20230601-01JURISDICTIONS & TAX REGIMES · UAE CORPORATE TAXUAE Corporate Tax Becomes RealThe UAE Corporate Tax regime began applying to financial years starting on or after 1 June 2023. The practical change was a new operating chain from accounts to taxable income, registration, records and returns.Read the analysis ↗8 MIN READ
Libertax editorial visualization for “MiCA: Europe Chooses a Single Crypto Rulebook”31 MAY 2023·FROM THE LIBERTAX ARCHIVEINS-20230531-01CRYPTO & DIGITAL ASSETS · CRYPTO TURNING POINTSMiCA: Europe Chooses a Single Crypto RulebookHow MiCA replaced much of Europe’s fragmented crypto-regulatory landscape with an EU framework — and why adoption in 2023 was only the beginning of implementation.Read the analysis ↗5 MIN READ
Libertax editorial visualization for “GPT-4: From Impressive Chatbot to General-Purpose Work Tool”14 MAR 2023·FROM THE LIBERTAX ARCHIVEINS-20230314-01AI & BORDERLESS WORK · AI TURNING POINTSGPT-4: From Impressive Chatbot to General-Purpose Work ToolGPT-4 widened the range of tasks for which generative AI looked professionally useful, while leaving a crucial limit intact: capability was not the same as reliability.Read the analysis ↗4 MIN READ
Libertax editorial visualization for “Golden Visa Does Not Decide Tax Residence”01 MAR 2023·FROM THE LIBERTAX ARCHIVEINS-20230301-01RESIDENCE & MOBILITY · PRACTICAL MYTHSGolden Visa Does Not Decide Tax ResidenceA UAE Golden Residency is an immigration status, not a tax-residence ruling. UAE domestic tax residence depends on statutory tests and evidence, while treaty residence is a separate analysis under the relevant DTA.Read the analysis ↗9 MIN READ
Libertax editorial visualization for “Switzerland, Singapore and the UAE: Three Models of the Small State”15 FEB 2023·FROM THE LIBERTAX ARCHIVEINS-20230215-01JURISDICTIONAL COMPETITIONSwitzerland, Singapore and the UAE: Three Models of the Small StateSwitzerland, Singapore and the UAE show why smallness is not an institutional model. They combine compact scale with radically different distributions of authority, openness and internal competition.Read the analysis ↗6 MIN READ
Libertax editorial visualization for “Portugal Starts Taxing Crypto: The End of a Simplified Story”30 DEC 2022·FROM THE LIBERTAX ARCHIVEINS-20221230-01JURISDICTIONS & TAX REGIMES · PORTUGAL FILESPortugal Starts Taxing Crypto: The End of a Simplified StoryPortugal's 2023 Budget introduced express tax rules for cryptoassets, ending the idea that every crypto transaction had one simple answer.Read the analysis ↗4 MIN READ
Libertax editorial visualization for “Spain’s Solidarity Tax: When Wealth Taxation Returns Through Another Door”27 DEC 2022·FROM THE LIBERTAX ARCHIVEINS-20221227-01HIGH-TAX POLICY · TAX PRESSURESpain’s Solidarity Tax: When Wealth Taxation Returns Through Another DoorHow Spain’s 2022 solidarity tax on large fortunes changed the wealth-tax landscape and why residence planning cannot be reduced to income-tax rates alone.Read the analysis ↗4 MIN READ
Libertax editorial visualization for “What the Crypto Winter Actually Taught Regulators”14 DEC 2022·FROM THE LIBERTAX ARCHIVEINS-20221214-01CRYPTO & DIGITAL ASSETS · CRYPTO TURNING POINTSWhat the Crypto Winter Actually Taught RegulatorsThe 2022 crypto winter was not only a story of falling prices. It exposed interconnectedness, leverage, concentration, custody and governance risks that policy had to treat as operating mechanisms.Read the analysis ↗7 MIN READ
Libertax editorial visualization for “Why Licensing Timelines Fail Before Filing”13 DEC 2022·FROM THE LIBERTAX ARCHIVEINS-20221213-01CRYPTO & DIGITAL ASSETS · REGULATED CRYPTOWhy Licensing Timelines Fail Before FilingThe regulator's review period is only one clock. Crypto projects often lose time earlier, while ownership, key people, capital, governance, evidence and operating systems are still incomplete.Read the analysis ↗7 MIN READ
Libertax editorial visualization for “30 November 2022: When AI Became an Operating Question”30 NOV 2022·FROM THE LIBERTAX ARCHIVEINS-20221130-01AI & BORDERLESS WORK · AI TURNING POINTS30 November 2022: When AI Became an Operating QuestionChatGPT did not invent artificial intelligence. It changed who could use advanced generative AI, how quickly they could experiment with it, and why every knowledge business suddenly had to pay attention.Read the analysis ↗5 MIN READ
Libertax editorial visualization for “The Hidden Payroll Behind a Regulated Crypto Business”26 NOV 2022·FROM THE LIBERTAX ARCHIVEINS-20221126-01CRYPTO & DIGITAL ASSETS · REGULATED CRYPTOThe Hidden Payroll Behind a Regulated Crypto BusinessA licence quote rarely captures the recurring people cost of a regulated crypto business. The useful model starts with functions and accountability, not a generic headcount.Read the analysis ↗7 MIN READ
Libertax editorial visualization for “FTX: Compliance Theatre Is Not Governance”15 NOV 2022·FROM THE LIBERTAX ARCHIVEINS-20221115-01CRYPTO & DIGITAL ASSETS · CRYPTO TURNING POINTSFTX: Compliance Theatre Is Not GovernanceFTX became a case study in the difference between appearing controlled and being constrained by real segregation, permissions, conflicts management and independent oversight.Read the analysis ↗7 MIN READ
Libertax editorial visualization for “Why MLRO Hiring Delays Crypto Projects”08 NOV 2022·FROM THE LIBERTAX ARCHIVEINS-20221108-01CRYPTO & DIGITAL ASSETS · REGULATED CRYPTOWhy MLRO Hiring Delays Crypto ProjectsIn regulated crypto, the MLRO is not a name added at the end of an application. Qualified people, fit-and-proper review and real accountability can become the critical path.Read the analysis ↗7 MIN READ
Libertax editorial visualization for “Privacy Is Not Opacity”31 OCT 2022·FROM THE LIBERTAX ARCHIVEINS-20221031-01PHILOSOPHY & STRATEGY · TAX PHILOSOPHYPrivacy Is Not OpacityPrivacy and transparency are not opposites. A legitimate international system can require verified ownership and tax information while limiting who may access, use and redistribute it.Read the analysis ↗6 MIN READ
Libertax editorial visualization for “The Licence Is the Easy Part”21 OCT 2022·FROM THE LIBERTAX ARCHIVEINS-20221021-01CRYPTO & DIGITAL ASSETS · REGULATED CRYPTOThe Licence Is the Easy PartA crypto licence answers a legal-permission question. It does not by itself build the people, capital, controls, banking and reporting needed to operate a regulated business.Read the analysis ↗7 MIN READ
Libertax editorial visualization for “7 October 2022: When Semiconductors Became Geopolitical Weapons”07 OCT 2022·FROM THE LIBERTAX ARCHIVEINS-20221007-01THE NEW WORLD ORDER7 October 2022: When Semiconductors Became Geopolitical WeaponsThe United States' 7 October 2022 controls on advanced computing and semiconductor manufacturing made explicit that leading-edge chips were no longer treated as ordinary commercial products.Read the analysis ↗3 MIN READ
Libertax editorial visualization for “The Company Managed from Exile”24 JUL 2022·FROM THE LIBERTAX ARCHIVEINS-20220724-01WORLD IN CONFLICTThe Company Managed from ExileA company does not have to move its registered office for its tax footprint to change. When directors, founders or key employees relocate because of war, corporate residence, effective management and permanent-establishment questions can move with them.Read the analysis ↗6 MIN READ
Libertax editorial visualization for “Why 'No Tax' Headlines Age Badly”15 JUL 2022·FROM THE LIBERTAX ARCHIVEINS-20220715-01PHILOSOPHY & STRATEGY · TAX PHILOSOPHYWhy 'No Tax' Headlines Age BadlyA zero-tax headline is a snapshot, not a durable tax position. Regime scope, conditions, residence, classification and reporting can change while the slogan survives.Read the analysis ↗7 MIN READ
Libertax editorial visualization for “War Creates Two Tax Homes”07 JUL 2022·FROM THE LIBERTAX ARCHIVEINS-20220707-01WORLD IN CONFLICTWar Creates Two Tax HomesForced displacement can create tax-residence facts in a new country while important ties remain in the old one. Immigration protection does not answer the tax question; domestic residence rules come first, and treaties may then have to resolve dual residence.Read the analysis ↗6 MIN READ
Libertax editorial visualization for “Source of Funds Is Now Business Infrastructure”30 JUN 2022·FROM THE LIBERTAX ARCHIVEINS-20220630-01BANKING & SUBSTANCE · BANKING REALITYSource of Funds Is Now Business InfrastructureSource-of-funds evidence should explain the economic origin, legal basis and payment path of material funds before a bank or counterparty has to ask.Read the analysis ↗6 MIN READ
Libertax editorial visualization for “When Your Passport Becomes a Compliance Risk”19 JUN 2022·FROM THE LIBERTAX ARCHIVEINS-20220619-01WORLD IN CONFLICTWhen Your Passport Becomes a Compliance RiskA passport can become a compliance data point without making its holder sanctioned or suspicious. Modern banking risk assessment looks at nationality, residence, business geography, counterparties and source of funds—but legitimate risk management is not the same as blanket exclusion.Read the analysis ↗5 MIN READ
Libertax editorial visualization for “W-8BEN or W-9? The Form Reveals the Tax Identity”10 JUN 2022·FROM THE LIBERTAX ARCHIVEINS-20220610-01CORPORATE STRUCTURES · THE LLC FILESW-8BEN or W-9? The Form Reveals the Tax IdentityThe correct US tax form starts with the identity and status of the payee, not the country of the bank account or the label attached to the company.Read the analysis ↗5 MIN READ
Libertax editorial visualization for “Sanctions Are a Parallel Legal System”01 JUN 2022·FROM THE LIBERTAX ARCHIVEINS-20220601-01WORLD IN CONFLICTSanctions Are a Parallel Legal SystemA transaction can be tax-compliant, contractually valid and still be prohibited or frozen by sanctions. Understanding that separate legal layer has become part of ordinary international business.Read the analysis ↗4 MIN READ
Libertax editorial visualization for “Terra, Yield and the Difference Between Return and Risk”15 MAY 2022·FROM THE LIBERTAX ARCHIVEINS-20220515-01CRYPTO & DIGITAL ASSETS · CRYPTO TURNING POINTSTerra, Yield and the Difference Between Return and RiskTerra's May 2022 collapse showed why a quoted yield is not a risk analysis. The mechanism behind the return, the peg, liquidity and counterparty structure matter more than the headline percentage.Read the analysis ↗7 MIN READ
Libertax editorial visualization for “Europe's Centralising Ratchet: When Integration Becomes Uniformity”09 MAY 2022·FROM THE LIBERTAX ARCHIVEINS-20220509-01JURISDICTIONAL COMPETITIONEurope's Centralising Ratchet: When Integration Becomes UniformityThe European problem is not cooperation itself but an institutional ratchet that can turn market integration into cumulative regulatory uniformity.Read the analysis ↗5 MIN READ
Libertax editorial visualization for “US LLC + Portugal NHR: Why ‘Foreign Dividends’ May Be the Wrong Starting Point”18 APR 2022·FROM THE LIBERTAX ARCHIVEINS-20220418-01PRACTICAL MYTHSUS LLC + Portugal NHR: Why ‘Foreign Dividends’ May Be the Wrong Starting PointPortuguese NHR treatment of a US LLC depends on Portuguese entity classification, the payment, source, management and the treaty—not the LLC’s US tax label alone.Read the analysis ↗6 MIN READ
Libertax editorial visualization for “Regulatory Capital Is Not Operating Capital”16 APR 2022·FROM THE LIBERTAX ARCHIVEINS-20220416-01CORPORATE STRUCTURES · REGULATED CRYPTORegulatory Capital Is Not Operating CapitalA prudential capital requirement protects a regulatory objective. It is not a substitute for the cash a crypto business needs to fund people, systems, delays and runway.Read the analysis ↗7 MIN READ
Libertax editorial visualization for “The NHR Trap for E-commerce Founders”15 APR 2022·FROM THE LIBERTAX ARCHIVEINS-20220415-01PRACTICAL MYTHSThe NHR Trap for E-commerce FoundersNHR did not turn an e-commerce business run from Portugal into passive foreign income: entity, work, management, source, VAT and each payment still require separate analysis.Read the analysis ↗6 MIN READ
Libertax editorial visualization for “CARF Begins: Crypto Enters the Tax-Transparency System”22 MAR 2022·FROM THE LIBERTAX ARCHIVEINS-20220322-01TRANSPARENCY & ENFORCEMENT · FROM CRS TO CARFCARF Begins: Crypto Enters the Tax-Transparency SystemWhat the OECD’s March 2022 consultation really meant: CARF was still a proposal, but the direction toward automatic crypto tax reporting had become explicit.Read the analysis ↗5 MIN READ
Libertax editorial visualization for “VARA 2022: Dubai Chooses Regulation, Not a Crypto Free-for-All”15 MAR 2022·FROM THE LIBERTAX ARCHIVEINS-20220315-01CRYPTO & DIGITAL ASSETS · CRYPTO TURNING POINTSVARA 2022: Dubai Chooses Regulation, Not a Crypto Free-for-AllWhy Dubai’s creation of VARA in 2022 mattered: the city chose a dedicated regulatory framework for virtual assets rather than treating crypto as an unregulated shortcut.Read the analysis ↗5 MIN READ
Libertax editorial visualization for “The UAE after February 2022: Safe Haven, Neutral Hub or Compliance Crossroads?”10 MAR 2022·FROM THE LIBERTAX ARCHIVEINS-20220310-01WORLD IN CONFLICTThe UAE after February 2022: Safe Haven, Neutral Hub or Compliance Crossroads?After Russia's invasion of Ukraine, the UAE became more important as a destination for people, capital and business. Its rise as a global hub occurred alongside stronger international pressure on financial-crime controls.Read the analysis ↗4 MIN READ
Libertax editorial visualization for “Why an Offshore Holding Can Make Banking Worse”03 MAR 2022·FROM THE LIBERTAX ARCHIVEINS-20220303-01BANKING & SUBSTANCE · BANKING REALITYWhy an Offshore Holding Can Make Banking WorseA cross-border holding can be legally and commercially useful, but each extra layer adds ownership, purpose, flow-of-funds and evidence questions that can increase banking friction.Read the analysis ↗6 MIN READ
Libertax editorial visualization for “24 February 2022: The Day Geography Returned”24 FEB 2022·FROM THE LIBERTAX ARCHIVEINS-20220224-01WORLD IN CONFLICT24 February 2022: The Day Geography ReturnedRussia's full-scale invasion of Ukraine exposed a weakness in frictionless globalisation: residence, capital, banking, energy and supply chains still depend on physical geography and political power.Read the analysis ↗4 MIN READ
Libertax editorial visualization for “The Day the UAE Announced Corporate Tax”31 JAN 2022·FROM THE LIBERTAX ARCHIVEINS-20220131-01JURISDICTIONS & TAX REGIMES · UAE CORPORATE TAXThe Day the UAE Announced Corporate TaxWhat businesses could actually know when the UAE announced federal Corporate Tax in January 2022 — and how the announcement became a full tax and accounting system.Read the analysis ↗5 MIN READ
Libertax editorial visualization for “The Discipline of Exit”20 DEC 2021·FROM THE LIBERTAX ARCHIVEINS-20211220-01JURISDICTIONAL COMPETITIONThe Discipline of ExitExit disciplines government only when the possibility of losing people, firms or capital is credible. Evidence shows real mobility responses, but their size varies and the costs can fall unevenly.Read the analysis ↗7 MIN READ
Libertax editorial visualization for “Portugal's NHR at Its 2021 Peak: The Promise and the Hidden Conditions”30 NOV 2021·FROM THE LIBERTAX ARCHIVEINS-20211130-01JURISDICTIONS & TAX REGIMES · PORTUGAL FILESPortugal's NHR at Its 2021 Peak: The Promise and the Hidden ConditionsA 2021 retrospective on why Portugal's NHR proposition became so compelling—and why its apparent simplicity concealed a demanding income-by-income analysis.Read the analysis ↗6 MIN READ
Libertax editorial visualization for “The Pandora Papers and the End of Casual Offshore Secrecy”15 OCT 2021·FROM THE LIBERTAX ARCHIVEINS-20211015-01TRANSPARENCY & ENFORCEMENT · THE TRANSPARENT WORLDThe Pandora Papers and the End of Casual Offshore SecrecyWhat the 2021 leak changed — not by making offshore structures illegal, but by showing how quickly private corporate records can become public, searchable and reputationally significant.Read the analysis ↗6 MIN READ
Libertax editorial visualization for “The Global Minimum Tax: The Day Tax Competition Changed”08 OCT 2021·FROM THE LIBERTAX ARCHIVEINS-20211008-01TAX COMPETITION · GLOBAL TAX ORDERThe Global Minimum Tax: The Day Tax Competition ChangedWhat the October 2021 two-pillar agreement actually changed, why the 15% minimum was never a tax on every company, and how Pillar Two became an operating system for large multinational groups.Read the analysis ↗5 MIN READ
Libertax editorial visualization for “Bitcoin Becomes Legal Tender: What El Salvador Was Really Testing”07 SEPT 2021·FROM THE LIBERTAX ARCHIVEINS-20210907-01CRYPTO & DIGITAL ASSETS · CRYPTO TURNING POINTSBitcoin Becomes Legal Tender: What El Salvador Was Really TestingEl Salvador's 2021 Bitcoin Law tested whether a state could turn a cryptoasset into national payment infrastructure. The 2025 reforms show the limits of confusing legal status with durable adoption.Read the analysis ↗7 MIN READ
Libertax editorial visualization for “Where Is a Company Really Managed?”31 AUG 2021·FROM THE LIBERTAX ARCHIVEINS-20210831-01CORPORATE STRUCTURES · STRUCTURES THAT WORKWhere Is a Company Really Managed?Incorporation, corporate tax residence, effective management and permanent establishment are separate questions. A UK–UAE example shows why the actual decision-making facts matter.Read the analysis ↗7 MIN READ
Libertax editorial visualization for “A Residence Permit Is Not Tax Residence”15 AUG 2021·FROM THE LIBERTAX ARCHIVEINS-20210815-01RESIDENCE & MOBILITY · PRACTICAL MYTHSA Residence Permit Is Not Tax ResidenceImmigration permission, domestic tax residence, treaty residence and a tax residence certificate answer different legal questions and must not be collapsed into one status.Read the analysis ↗6 MIN READ
Libertax editorial visualization for “Why Online Founders Fell in Love with US LLCs — and What They Missed”08 AUG 2021·FROM THE LIBERTAX ARCHIVEINS-20210808-01CORPORATE STRUCTURES · THE LLC FILESWhy Online Founders Fell in Love with US LLCs — and What They MissedA US LLC can be easy to form, but federal classification, foreign tax treatment and reporting remain separate questions.Read the analysis ↗4 MIN READ
Libertax editorial visualization for “The 183-Day Rule Is Not a Magic Cloak”01 AUG 2021·FROM THE LIBERTAX ARCHIVEINS-20210801-01RESIDENCE & MOBILITY · PRACTICAL MYTHSThe 183-Day Rule Is Not a Magic CloakTax residence is not determined by one universal day count. Domestic law comes first, treaty analysis comes later, and evidence must match the facts.Read the analysis ↗6 MIN READ
Libertax editorial visualization for “Remote Work Broke the Old Map of Tax Residence”31 JUL 2021·FROM THE LIBERTAX ARCHIVEINS-20210731-01RESIDENCE & MOBILITY · BORDERLESS WORKRemote Work Broke the Old Map of Tax ResidenceThe remote-work shock turned occasional cross-border questions into recurring residence, permanent-establishment, payroll and social-security problems. Those layers remain legally distinct.Read the analysis ↗7 MIN READ
Libertax editorial visualization for “EU VAT OSS and the Non-Union Scheme”01 JUL 2021·FROM THE LIBERTAX ARCHIVEINS-20210701-02DIGITAL TAX · DIGITAL BUSINESS TAXEU VAT OSS and the Non-Union SchemeThe non-Union OSS can centralise VAT reporting for certain B2C services, but it is a compliance mechanism rather than an exemption.Read the analysis ↗4 MIN READ
Libertax editorial visualization for “The Tax Authority Inside the Platform”01 JUL 2021·FROM THE LIBERTAX ARCHIVEINS-20210701-01TRANSPARENCY & ENFORCEMENT · THE TRANSPARENT WORLDThe Tax Authority Inside the PlatformHow digital platforms became part of the tax-information infrastructure — and why automated reporting increases the need for reconciliation rather than replacing tax analysis.Read the analysis ↗5 MIN READ
Libertax editorial visualization for “When the UAE Opened Mainland Companies to Full Foreign Ownership”01 JUN 2021·FROM THE LIBERTAX ARCHIVEINS-20210601-01JURISDICTIONS & TAX REGIMES · UAE TRANSFORMATIONWhen the UAE Opened Mainland Companies to Full Foreign OwnershipHow the UAE’s 2021 ownership reform changed the mainland/free-zone calculation — and why 100% ownership never meant zero regulatory complexity.Read the analysis ↗5 MIN READ
Libertax editorial visualization for “The Europe We Lost: Small States, Competing Jurisdictions and Political Escape”23 APR 2021·FROM THE LIBERTAX ARCHIVEINS-20210423-01JURISDICTIONAL COMPETITIONThe Europe We Lost: Small States, Competing Jurisdictions and Political EscapeEurope became exceptional as a culturally connected civilisation whose power remained divided among cities, cantons, republics, principalities and kingdoms. Its loss was not a particular map, but the disappearance of credible alternatives to political monopoly.Read the analysis ↗13 MIN READ
Libertax editorial visualization for “DAC7: The Platform Economy Stops Being Invisible”09 APR 2021·FROM THE LIBERTAX ARCHIVEINS-20210409-02TRANSPARENCY & ENFORCEMENT · THE TRANSPARENT WORLDDAC7: The Platform Economy Stops Being InvisibleWhy the EU’s 2021 platform-reporting directive changed tax enforcement for sellers and service providers without creating a new tax on every platform transaction.Read the analysis ↗5 MIN READ
Libertax editorial visualization for “Libertax Begins: A Five-Year View of a Changing Tax World”09 APR 2021·FROM THE LIBERTAX ARCHIVEINS-20210409-01LIBERTAX ARCHIVE · FIVE YEARS OF LIBERTAXLibertax Begins: A Five-Year View of a Changing Tax WorldFrom 9 April 2021, the founding date of Libertax International Ltd, a retrospective on the tax, transparency and regulatory shifts that changed international structuring over the next five years.Read the analysis ↗6 MIN READ

Libertax · Cross-border business and tax solutions

Libertaxinfo@liber.tax